Apex and Chainlink Demonstrate Swift-Aligned Compliance for Tokenized Bonds
Apex, Chainlink, T-REX Network and the ERC-3643 Association demonstrated reusable compliance for on-chain bonds. The framework combines Swift standards with identity checks and cross-chain infrastructure.
 By Matthew Brienen
Last updated
Keeping the rules with the asset
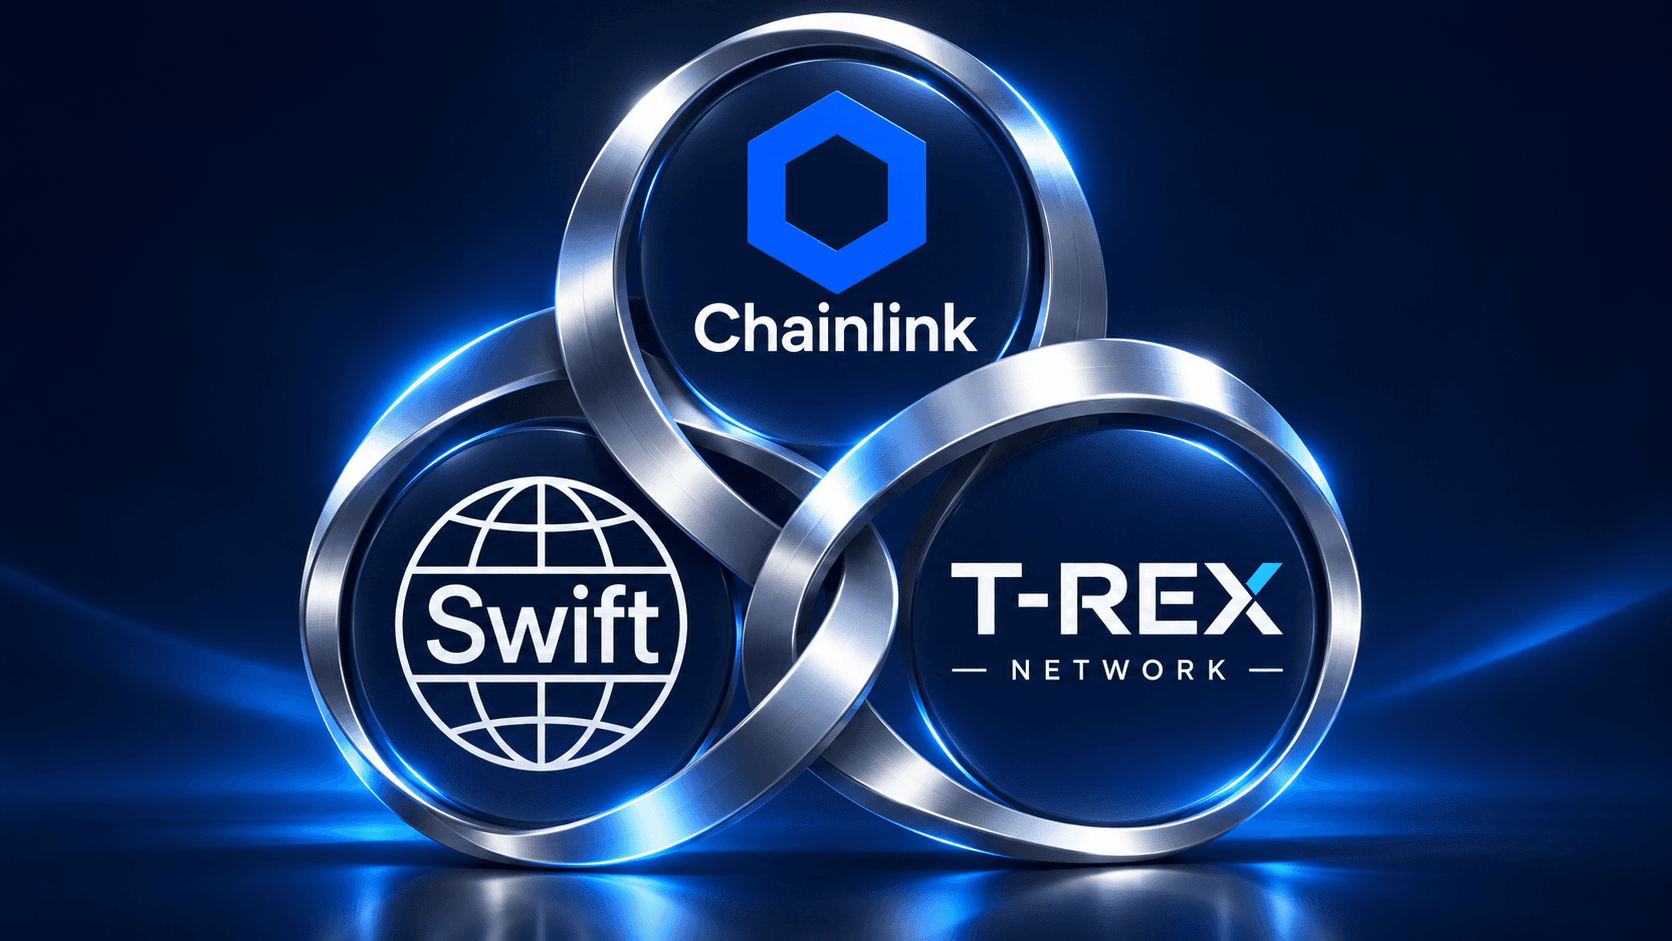
Apex Group, Chainlink, T-REX Network and the ERC-3643 Association have demonstrated a compliance framework for on-chain bonds that uses Swift standards. Apex announced the work on November 4 and said Swift has joined the ERC-3643 Association.
The initiative addresses a practical obstacle in tokenized finance: an asset moving between blockchains still needs consistent ownership and eligibility rules. The participants describe a framework intended to reuse those rules across supported networks, reducing the need to rebuild compliance for each environment.
Apex supplies the asset-servicing and operational setting. T-REX provides deployment and distribution infrastructure with a common record, while ERC-3643 supplies the modular compliance standard. Swift's standards help keep the on-chain representation consistent with established financial-market data models and practices.
Where Chainlink fits
According to Apex, Chainlink contributes cross-chain transfers through its Cross-Chain Interoperability Protocol, or CCIP; policy enforcement through its Automated Compliance Engine, or ACE; and pricing information through Data Streams. Those are distinct functions within the bond implementation.
CCIP's documentation describes infrastructure for sending messages and transferring tokens between supported blockchain networks. That connection is useful when an issuer and an investor use different networks, but moving a token is only one requirement. The receiving environment must also interpret and apply the asset's restrictions.
The demonstration brings those functions into one workflow. For institutions assessing it, the question is whether a transfer preserves the relevant asset record and required checks throughout the journey. A successful technical connection alone would not answer every question about how a regulated instrument is administered.
ERC-3643 makes eligibility part of transfers
The ERC-3643 specification describes a permissioned token standard with an identity registry and configurable compliance rules. Before an ordinary transfer succeeds, the recipient must have a verified identity carrying the required claims. Frozen wallets, insufficient available balances or a paused token can also prevent movement.
An issuer can configure restrictions such as eligible jurisdictions or holding limits. In that model, possessing a compatible blockchain address is only one requirement for receiving an asset. The token's rules determine whether that particular recipient may hold it.
Consider an illustrative bond restricted to eligible investors in certain jurisdictions. A transfer to a technically valid address could still fail because the recipient lacks the necessary verification. That rejection would be the expected operation of the compliance system. It would not, on its own, indicate a broken blockchain connection.
The standard also includes administrative powers and special transaction paths. Institutions evaluating a deployment need to understand who controls those powers as well as which rules apply to routine transfers.
One record across supported networks
T-REX describes its approach as maintaining coherent ownership and compliance across chains, venues and applications. Its materials distinguish identity claims from publishing personal know-your-customer information: the record can establish eligibility without making the underlying personal data public.
The network also describes authorized roles for activities such as issuance, redemption, freezing and recovery. These features help explain why institutional tokenization involves more than creating a transferable digital unit. The instrument has an operational life after issuance, including changes that must be reflected consistently wherever it is distributed.
For an investor, wider distribution can mean access through a supported network they already use. For an issuer, maintaining a common record can reduce the need to reconcile separate versions of the same asset. Those are intended benefits of the design; their scale depends on actual deployments and usage.
What the announcement establishes
The work demonstrates a bond implementation combining existing market standards with programmable rules and cross-chain infrastructure. It does not establish that every Swift member is now using these systems, or that an unrestricted public market has opened for the bonds.
The next evidence to watch is operational: which assets use the framework, which networks and counterparties support them, and how issuance and subsequent transfers perform. For LINK holders, an infrastructure role is relevant adoption news, but transaction activity and commercial economics still need to be measured before drawing conclusions about token demand.