UK, Singapore and Thailand Complete Cross-System FX Settlement Trial
Project Meridian FX APAC demonstrated coordinated FX settlement across three central-bank test systems. The trial linked different technologies and explored liquidity savings, while leaving live implementation work ahead.
 By Matthew Brienen
Last updated
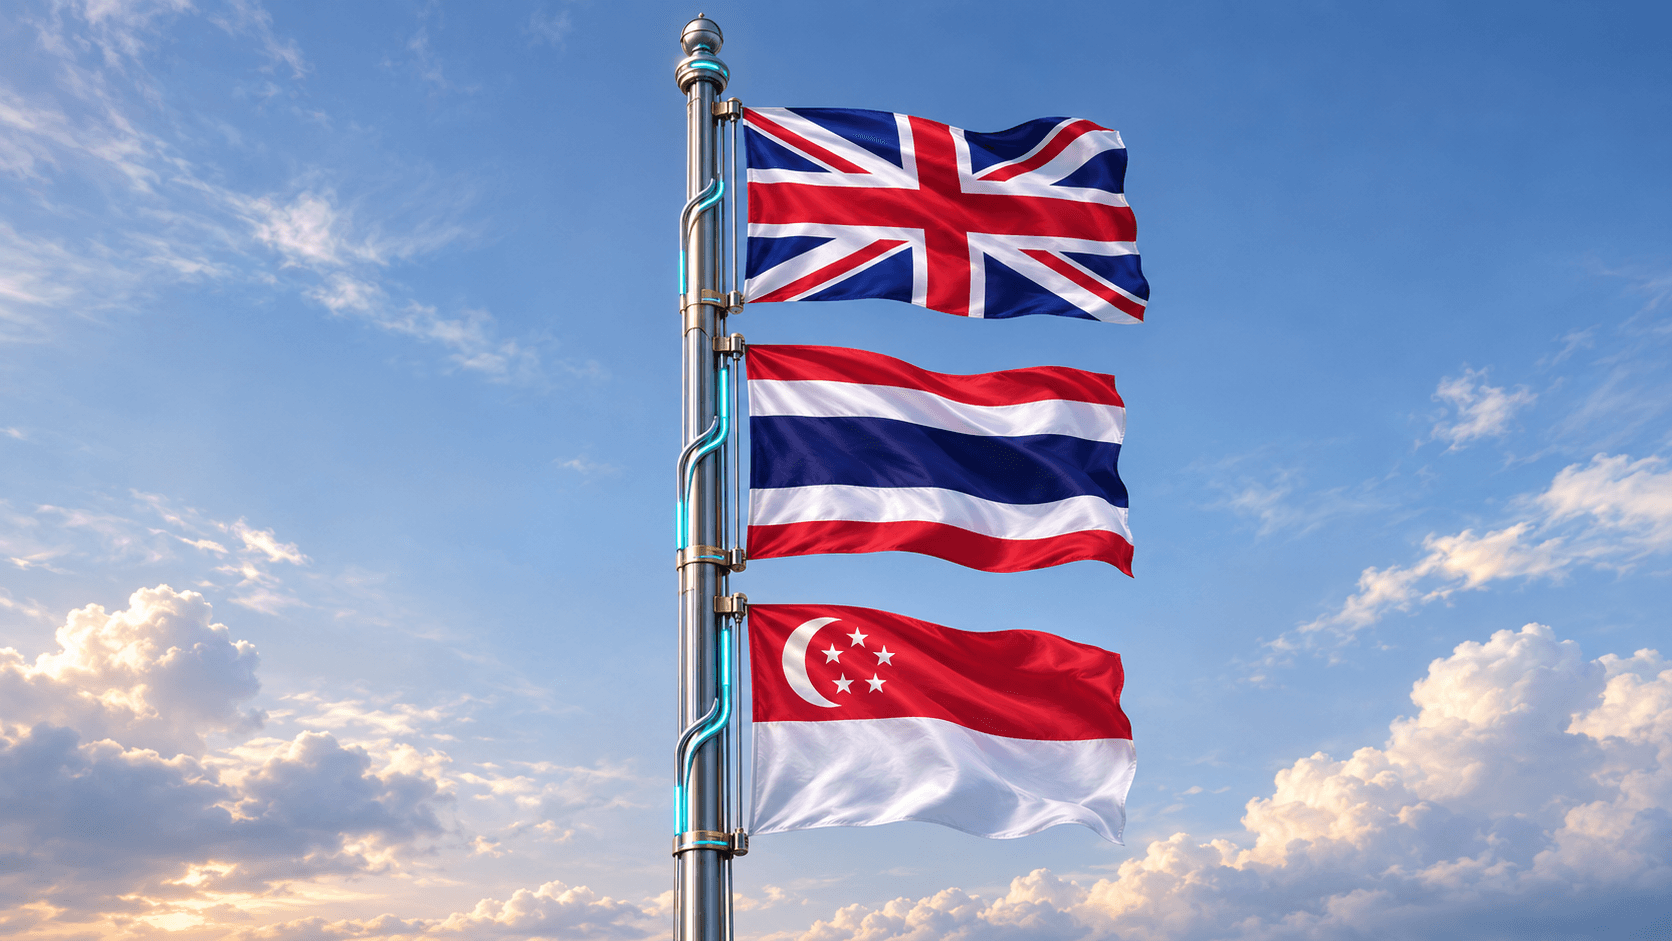
Three central banks have completed a trial linking different systems for foreign-exchange settlement.
The Bank of England, Monetary Authority of Singapore and Bank of Thailand published Project Meridian FX APAC findings on November 13. Their experiment demonstrated coordinated settlement across traditional and distributed-ledger environments, with further technical and policy work needed before a comparable live cross-border service.
Making both sides of a trade settle
A foreign-exchange transaction involves delivering one currency in return for another. Payment-versus-payment, or PvP, links the transfers so that one side does not pay away its currency without receiving the other side. The project tested whether that protection could work across systems with different designs.
Partior developed and integrated the trial's Synchronisation Operator prototype. Its job was to coordinate the separate settlement systems, reserve the required funds and instruct settlement when the linked payments were ready.
The distinction is useful for understanding financial infrastructure. Separate systems do not necessarily have to be replaced by one shared ledger to work together. They need a way to coordinate the conditions under which funds move, with enough information to establish what has happened when a step fails.
Different systems required different connections
The test involved the Bank of England's simulated RTGS environment, Thailand's Project SAN and a non-production configuration of Singapore's SGD Testnet. Their architectures differed, including how funds could be reserved and how a third party could initiate settlement.
The operator used system-specific connections to accommodate those differences. In the Singapore setup, a dedicated bank-owned wallet helped replicate funds reservation under the participant's authorization. That arrangement introduced responsibilities beyond those of an operator that simply coordinates transfers without handling funds.
The technical report also distinguishes failures before and after commitment. Before commitment, reservations could be released if a required step failed. After commitment, the process pursued completion of outstanding payments instead of reversing a leg that had already settled.
That is why an all-or-nothing design still requires detailed recovery rules. A temporary outage can occur after one system has acted. The operator and participating systems need reliable transaction status and a way to finish the linked transfer without accidentally submitting the same payment twice.
The liquidity benefit needs further testing
Meridian FX APAC also demonstrated multilateral net settlement across the three environments. Offsetting eligible obligations can reduce the amount of liquidity participants need to provide, while retaining the link between the currency payments.
The executive summary says the trial tested selected problems, including insufficient funds, invalid account identifiers and temporary outages. Those results are encouraging, but the experiment did not reproduce the full FX trade lifecycle or live operating conditions.
The technical work assumed overlapping system availability. Differences in operating hours and the expiry of reserved funds remain areas for further study. A service connecting multiple time zones needs to handle those constraints without tying up liquidity for excessive periods.
Legal finality remains a separate question
The policy report examines the legal and oversight issues that would arise in a live arrangement. A technical process that coordinates transfers does not automatically establish the same legal outcome across several jurisdictions. Responsibilities, enforceability and the treatment of funds still need to be clear.
That matters if an operator takes on additional functions to bridge differences between systems. Its risk profile depends on what it actually does, including whether it controls funds or performs netting, rather than only the name given to the service.
The Bank of England plans a live synchronisation interface in 2028. The project does not establish an equivalent implementation commitment by Singapore or Thailand, and the three-country trial should not be described as a production launch.
For tokenization and digital-finance markets, the result shows a possible route for connecting new settlement technology with existing central-bank infrastructure. It does not designate a public cryptocurrency as the settlement asset or establish demand for an investment token. The progress is in coordinating the systems, with live scale, operating conditions and legal arrangements still to be worked through.